Skip to content
WiT Access

Property

Property tax across borders

Understand the tax questions that can arise when you buy, hold, rent, inherit or sell property in another country.

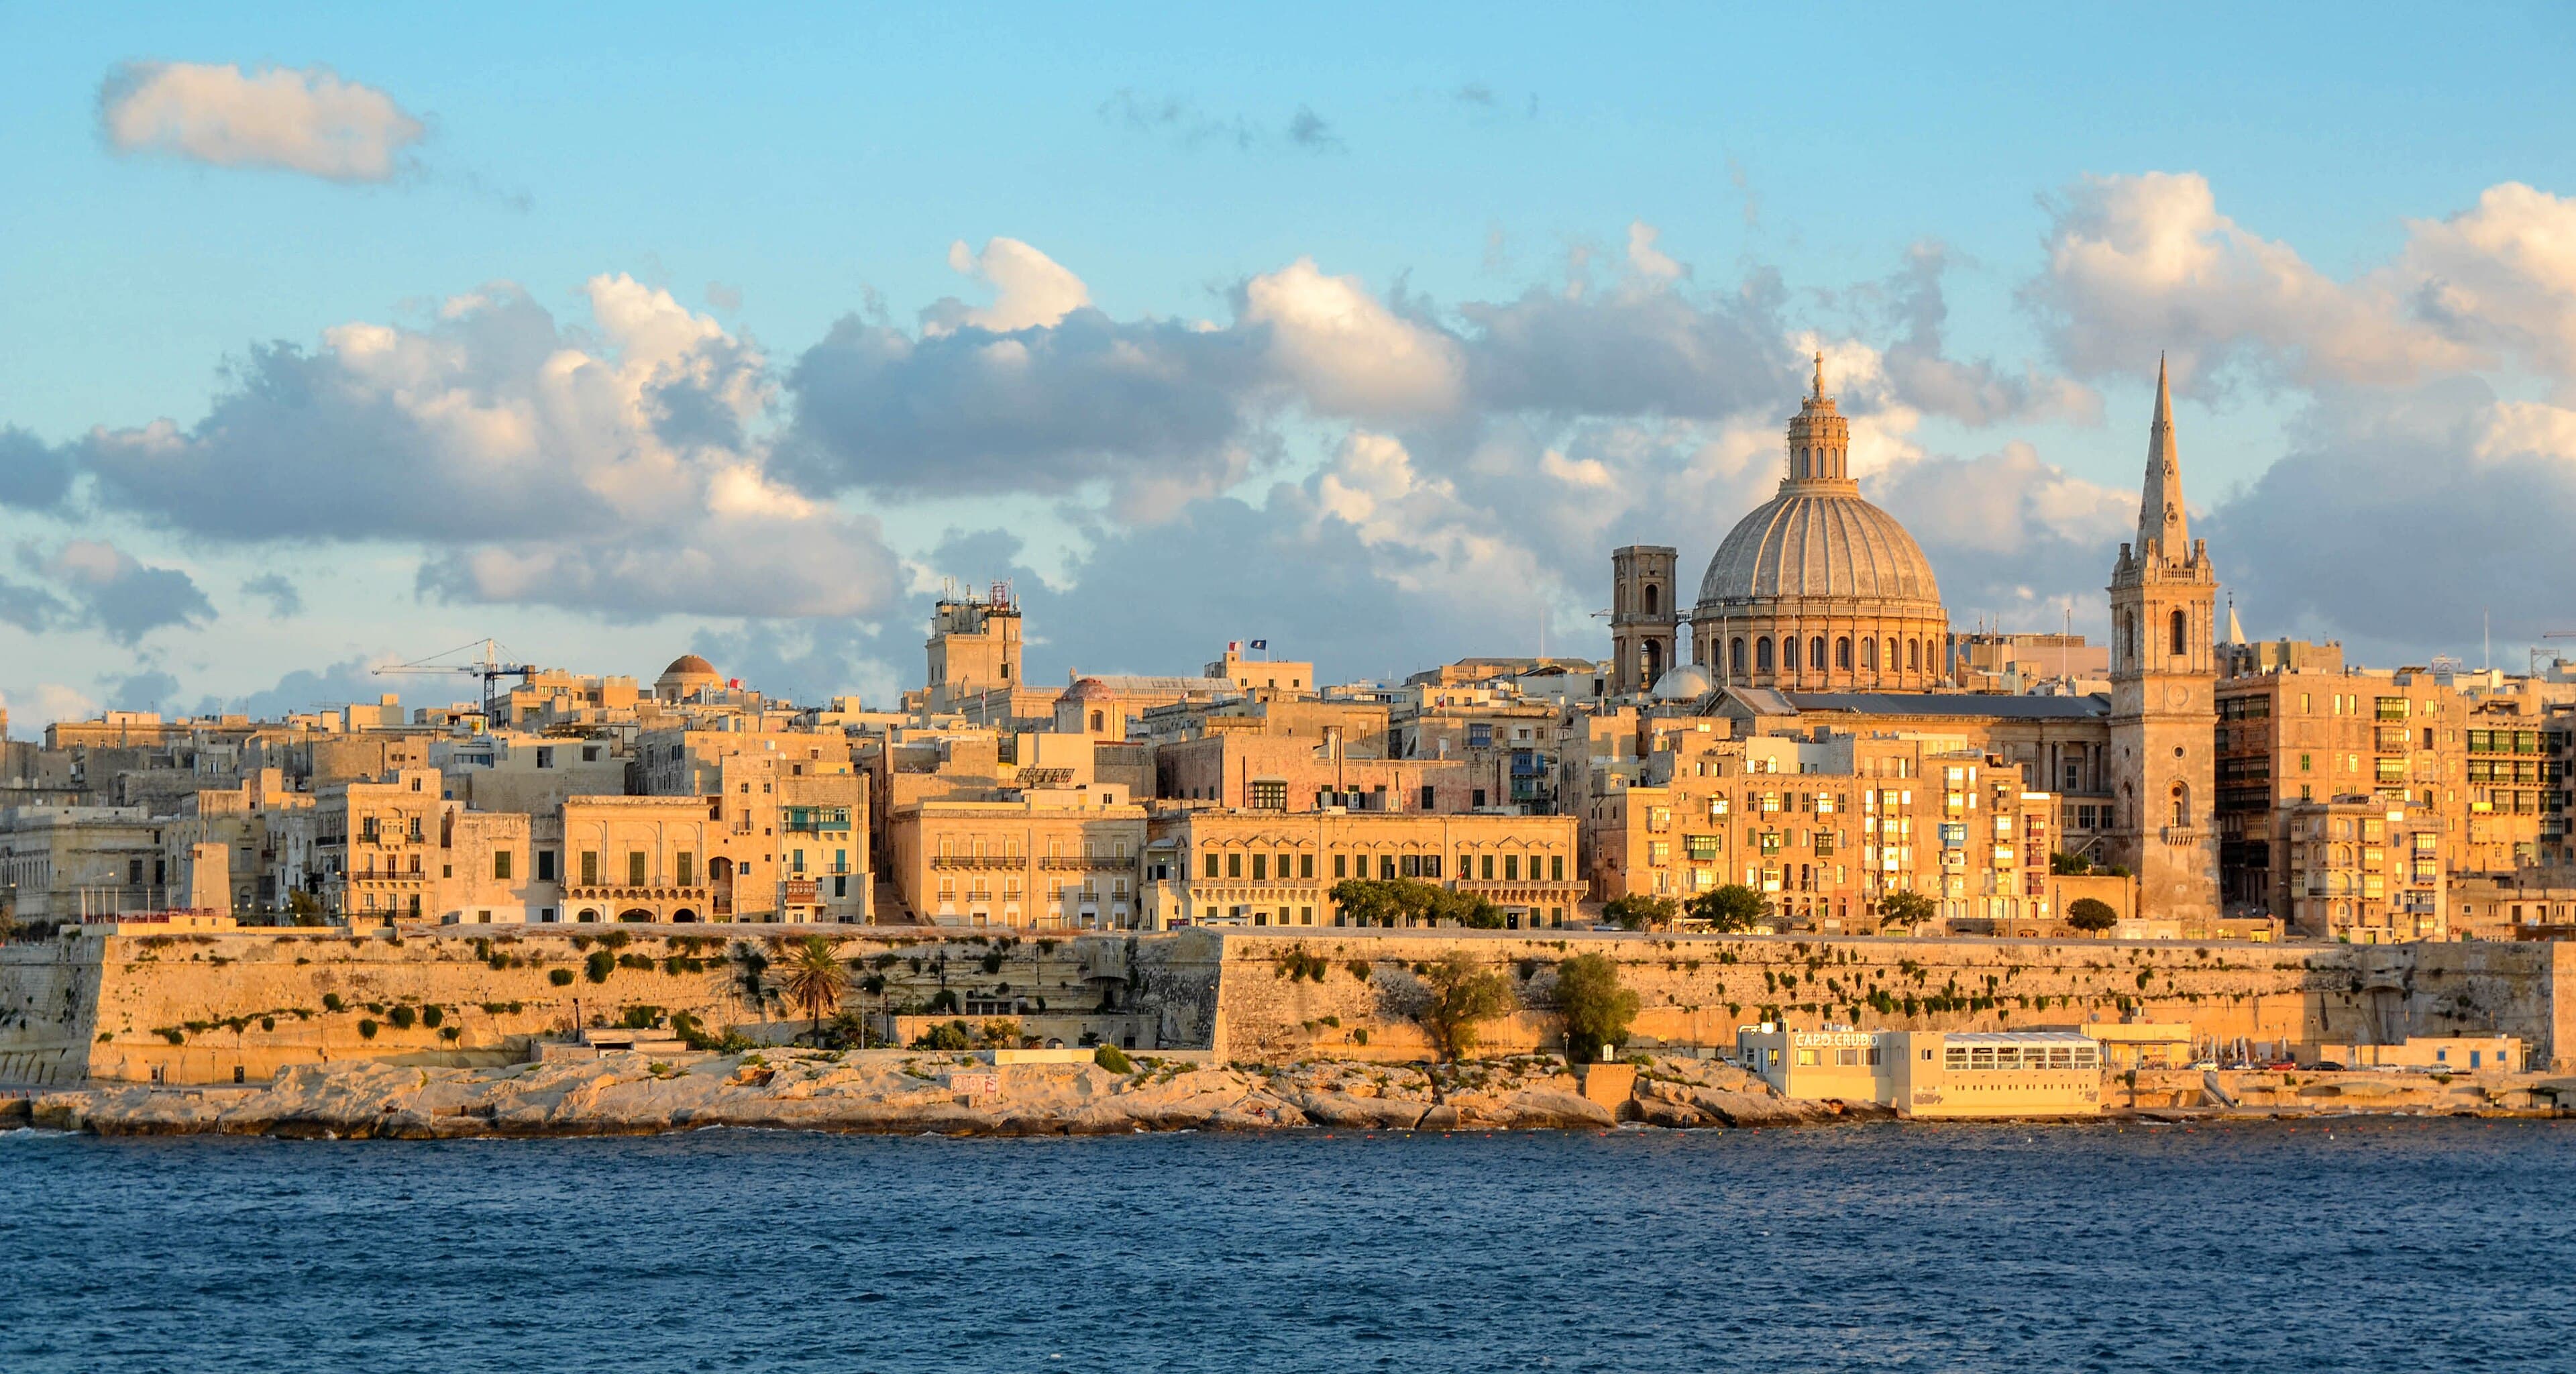
A limestone harbour city with domes and a fortified waterfront in warm evening light

Property often remains connected to the country where it sits, even when the owner lives somewhere else.

Purchase, annual ownership, rent, a sale and an inheritance can each create a tax question. Some sit in the country of the property. Some sit where you are resident. A treaty may be relevant. It does not, by itself, remove the tax or the filing. This page names the categories. It does not state a rate, an exemption or a bill.

Property tax is usually a combination of property location, owner residence, property use, ownership structure and the tax rules of one or more countries.

How the property is owned can change the analysis. That discussion is on ownership structures, and it is not a recommendation to use a company.

Purchase

Costs at completion are not all the same kind of tax

Transfer taxes, VAT or a similar tax on a new property, stamp or registration duties, and local fees are categories a lawyer should price for the property in front of you. They can depend on the region, the value, whether the property is new, and whether the buyer is resident. A national average copied from a blog is not that figure. Transaction costs such as notary and legal fees sit beside the tax. They are not tax, and they still belong in the budget.

  1. 01

    Buy

    Transfer taxes, VAT or a similar sales tax, registration and local fees — as categories, not rates.

  2. 02

    Hold

    Annual property taxes, and any wealth-style tax a country uses. Separate from community charges.

  3. 03

    Rent

    Local tax on income, and a possible report where you live.

  4. 04

    Sell

    A gain, cost basis, and any tax withheld from the proceeds.

  5. 05

    Inherit

    The country of the property and the country of the person who inherits may both ask.

Each year

Annual property taxes are separate from community charges

A local property tax is a charge for owning. Some countries also use a wealth-style tax that can include property. Community or municipal service charges are often a payment to a building or a town for services, and they should be read as that, not folded into “tax” without asking. All of them continue while you own the property, including in years you do not visit.

Income

Rent can be taxed where the property is and reported where you live

Gross rent, the expenses a system allows, and the filings are local. Depreciation, where a system uses it, is one of those local rules — ask whether it exists. Do not import a deduction from home. The country where you are tax resident may also expect the income on a return, with relief if foreign tax has been paid. Licensing and occupancy rules are not tax, and they can still stop the letting.

A gain

A sale needs a cost basis, not only a sale price

How a gain is measured, which purchase costs and improvements count, and whether tax is withheld from the proceeds are questions for the country of the property. Timing — which tax year the sale falls in — can matter if you are also moving. A gain measured in the property’s currency can look different in the currency of your residence. Keep the contracts and the invoices. This page does not compute a gain.

Living elsewhere

A non-resident owner can still have a local filing

Absence is not an exemption. Non-resident owners are often within the tax system of the country where the property sits, for purchase, for income, for a sale, or for an annual charge. The detail is local. Ask the lawyer or tax adviser who acts there, including when the property is empty.

Where you live

Residence-country reporting can exist when the tax was paid abroad

Foreign property, rental income and a gain can be reportable where you are tax resident even if you have already dealt with the country of the property. Tax residency is the question of which system that is. Reporting and tax due are separate.

Taken at source

Tax can be kept back from rent or from a sale

A payer, a tenant’s agent or a buyer’s notary may withhold tax before you receive the balance. Whether you can reclaim any of it, and what form that needs, is a local process. A treaty may be relevant to the rate. This page states no rate. Ask what will actually be deducted on this payment.

Two countries

Double taxation is a relief question, not a reason to ignore either return

The country of the property is often the source. The country of residence may also tax, and may give a credit, an exemption or another form of relief. A treaty between them may set out a method. It does not apply itself, and it does not eliminate property tax in every case. Double-tax treaties explains that limit.

A company in between

Company ownership is a second taxpayer, not a shortcut

Tax on the company, tax on you when value comes out, and reporting of the foreign company can all exist together. Local rules may also limit or charge corporate owners differently from individuals. Ask before the company signs. The legal split is on ownership structures.

Death

Inheritance and estate taxes follow the property and the people

The country where the property sits, and a country connected to you or to the person who inherits, may each have a question. Wealth and inheritance rules can differ by region. A will from home may not deal with the property cleanly. Cross-border estate planning is the document side of the same problem.

The file

Records are what make a later gain explainable

  • Purchase contract
  • Acquisition costs
  • Improvements
  • Rental income
  • Expenses
  • Tax filings
  • Sale documents

Due diligence

Questions worth asking a tax adviser before you rely on a figure

01Which taxes apply when I buy this property?

Ask for transfer taxes, any VAT or sales tax, registration and local fees on this property. Rates vary. This page states none.

02What do I pay each year for owning it?

Ask about local property tax and any wealth-style tax, and keep community or municipal service charges as a separate line. They are not all tax.

03If I let it, where is the income taxed and where is it reported?

Ask the country of the property and the country where you are resident. Expenses you can deduct are a local rule.

04What happens when I sell?

Ask how a gain is measured, whether tax can be withheld from the price, and which improvements count. Keep the invoices.

05Does a change in currency change the gain where I am resident?

Ask. A gain measured in one currency can look different in another. This page does not calculate it.

06I live elsewhere. Do I still have a filing where the property is?

Often a non-resident owner still has a local question. Ask. Do not assume absence removes it.

07Does my country of residence want a report even if tax is paid abroad?

Ask. Reporting and tax are not the same duty.

08Is a treaty relevant?

A treaty may allocate rights or allow relief. It does not remove property tax because it exists. See double-tax treaties.

09How would foreign tax relief be claimed?

Ask whether any credit or exemption has to be claimed, and with what evidence. Relief is not automatic.

10If a company owns the property, whose tax is it?

Ask about the company and about you as shareholder. They can both have a filing. See ownership structures.

11What inheritance or estate tax could apply?

Ask the country of the property and the country connected to you or your heirs. Regional differences can matter.

12Which records should I keep from the day I buy?

Contracts, costs, improvements and filings. Reconstructing a cost basis later is harder.

Watch for

Mistakes that show up when you sell or when you file

  • Budgeting only the purchase price
  • Ignoring a report in the country where you live
  • Throwing away invoices for improvements
  • Assuming a treaty eliminates property tax
  • Buying through a company without a tax analysis
  • Leaving inheritance until after a death

Ask the lawyer or tax adviser for a figure for this property. A published average is not that figure.

Professional support

When a local tax adviser may be appropriate

This page identifies questions. It does not prepare a return. Advice may be appropriate when you buy, when you start to let, when you sell, when a company is put on the title, or when the property will pass on death — particularly if two countries are involved.

Compare property tax providers

Property tax can involve more than one country and more than one type of tax

Property tax is usually a combination of property location, owner residence, property use, ownership structure and the tax rules of one or more countries.

Compare property-tax providers by purchase-tax support, annual filings, rental-income tax, capital gains, inheritance / estate tax, tax-residency interaction, entity ownership and cross-border coordination.

A provider focused on digital non-resident filings is very different from a cross-border private-client tax adviser or fiduciary group. Compare the service model before comparing price.

Start with the tax question

What are you trying to sort out?

What to compare

Different providers solve different property-tax problems

  1. 01

    Purchase taxes

    Does the provider advise on acquisition taxes and costs?

  2. 02

    Annual filings

    Can they handle recurring owner or non-resident filings?

  3. 03

    Rental income

    Can they advise on or file rental-income tax?

  4. 04

    Capital gains

    Can they support tax on a sale or disposal?

  5. 05

    Inheritance

    Can they coordinate property within estate planning?

  6. 06

    Tax residence

    Can they deal with residence changing across borders?

  7. 07

    Entity ownership

    Can they advise on company or trust ownership?

  8. 08

    Ongoing compliance

    Is the service adviser-led or digitally managed?

Filter property tax providers

4 providers listed for comparison.

  • Blevins Franks

    Blevins Franks

    Cross-border tax and wealth adviser

    Cross-border personal tax, property-related income and gains, estate tax and residence planning for UK nationals in the European markets it names. This is adviser-led. It is not a global filing platform.

    Best aligned with
    UK nationals in selected European markets
    Global reach
    Regional / Europe
    Primary audience
    UK nationals living in or moving to France, Spain, Portugal, Cyprus, Malta, Monaco and the UK
    Tax scope
    Cross-border personal tax
    Purchase tax
    Advisory-led
    Annual filings
    Advisory-led
    Rental income
    Strong
    Capital gains
    Strong
    Inheritance / estate
    Exceptional
    Tax residence
    Exceptional
    Entity ownership
    Available
    Cross-border
    Exceptional
    Ongoing compliance
    Adviser-led
    Pricing model
    Advisory engagement
    Service model
    Adviser-led

    The published audience is primarily UK nationals in selected European countries. Do not read this as a global property-tax filing service.

  • Equiom logo

    Equiom

    Private-client tax, fiduciary and real-estate structuring provider

    Private-client tax and fiduciary work integrated with international real-estate ownership. This is a professional administration model, not a mass-market filing service.

    Best aligned with
    HNW owners · family offices
    Global reach
    High
    Primary audience
    HNW private clients, family offices, international property owners and investors
    Tax scope
    Private-client tax and structuring
    Purchase tax
    Strong
    Annual filings
    Strong
    Rental income
    Available
    Capital gains
    Available
    Inheritance / estate
    Strong
    Tax residence
    Strong
    Entity ownership
    Exceptional
    Cross-border
    Strong
    Ongoing compliance
    Professional administration
    Pricing model
    Engagement-specific
    Service model
    Private-client administration

    Tax effects depend on the property jurisdiction, residence, ownership vehicle, use and succession. Advice must be delivered by the relevant qualified entity.

  • Estity logo

    Estity

    Digital Spanish property tax and document platform

    A digital platform for recurring Spanish property-owner filings, documents and reminders. It is not a substitute for broader cross-border tax advice.

    Best aligned with
    Foreign Spanish property owners
    Global reach
    Spain specialist
    Primary audience
    Non-resident Spanish property owners, buyers and landlords
    Tax scope
    Spanish owner compliance
    Purchase tax
    Limited
    Annual filings
    Core
    Rental income
    Core
    Capital gains
    Guidance
    Inheritance / estate
    Not core
    Tax residence
    Not core
    Entity ownership
    Not core
    Cross-border
    Owners living outside Spain
    Ongoing compliance
    Digital recurring platform
    Pricing model
    Published subscription and filing prices
    Service model
    Digital platform

    Spain-specific. The platform is not a substitute for broader cross-border tax advice. Confirm the current filing status before you rely on it.

  • SpainFiscal

    SpainFiscal

    Spanish property tax and compliance specialist

    Spanish tax and compliance for foreign owners of property in Spain, including representation and recurring filings. This is not a global personal-tax adviser.

    Best aligned with
    Foreign owners · non-resident landlords · buyers
    Global reach
    Spain specialist
    Primary audience
    Foreign property owners, non-resident landlords, buyers and international clients with Spanish tax obligations
    Tax scope
    Spanish non-resident tax
    Purchase tax
    Available
    Annual filings
    Core
    Rental income
    Core
    Capital gains
    Available
    Inheritance / estate
    Specialist support
    Tax residence
    Available
    Entity ownership
    Available
    Cross-border
    Foreign-owner focused
    Ongoing compliance
    Recurring service
    Pricing model
    Confirm the current fee
    Service model
    Digital and professional

    Spain-specific. Tax advice and filing scope should be matched to the client’s residence, property use and transaction.

Compare property tax providers

Short published facts only. These labels describe the provider’s own materials. They are not ratings, and they are not tax rates.

A Spanish filing platform and a cross-border private-client adviser do not take the same instruction.

Property tax providers compared by published scope.
ProviderProvider typeBest aligned withGlobal reachOwner complianceCapital gainsInheritance / estateCross-border / structureView
Blevins Franks
Blevins Franks
Cross-border tax adviserUK nationals in selected European marketsRegional / EuropeAdvisory filings · strong rentalStrongExceptionalExceptional residence · entity availableView
Equiom logo
Equiom
Private-client fiduciaryHNW owners · family officesHighStrong filings · rental availableAvailableStrongStrong residence · exceptional entitiesView
Estity logo
Estity
Digital tax platformForeign Spanish property ownersSpain specialistCore filings · core rentalGuidanceNot coreNot coreView
SpainFiscal
SpainFiscal
Property-tax specialistForeign owners · non-resident landlords · buyersSpain specialistCore filings · core rentalAvailableSpecialist supportResidence available · entity availableView
Property tax providers compared by published scope.
ProviderBest aligned withOwner complianceInheritance / estateView
Blevins Franks
Blevins Franks
UK nationals in selected European marketsAdvisory filings · strong rentalExceptionalView
Equiom logo
Equiom
HNW owners · family officesStrong filings · rental availableStrongView
Estity logo
Estity
Foreign Spanish property ownersCore filings · core rentalNot coreView
SpainFiscal
SpainFiscal
Foreign owners · non-resident landlords · buyersCore filings · core rentalSpecialist supportView
  • Provider type
    Cross-border tax adviser
    Best aligned with
    UK nationals in selected European markets
    Annual filings
    Advisory-led
    Rental income
    Strong
    Capital gains
    Strong
    Inheritance / estate
    Exceptional
    Tax residence
    Exceptional
    Cross-border
    Exceptional
    View provider
  • Provider type
    Private-client fiduciary
    Best aligned with
    HNW owners · family offices
    Annual filings
    Strong
    Rental income
    Available
    Capital gains
    Available
    Inheritance / estate
    Strong
    Tax residence
    Strong
    Cross-border
    Strong
    View provider
  • Provider type
    Digital tax platform
    Best aligned with
    Foreign Spanish property owners
    Annual filings
    Core
    Rental income
    Core
    Capital gains
    Guidance
    Inheritance / estate
    Not core
    Tax residence
    Not core
    Cross-border
    Owners living outside Spain
    View provider
  • Provider type
    Property-tax specialist
    Best aligned with
    Foreign owners · non-resident landlords · buyers
    Annual filings
    Core
    Rental income
    Core
    Capital gains
    Available
    Inheritance / estate
    Specialist support
    Tax residence
    Available
    Cross-border
    Foreign-owner focused
    View provider

Understand the tax layer

Property taxation changes at different stages of ownership

  • Buying

    Transfer taxes, VAT or a similar sales tax, stamp-type taxes and transaction costs.

  • Owning

    Annual property taxes and non-resident owner filings.

  • Renting

    Rental income and the cost rules of that tax system.

  • Selling

    Capital gains, withholding and disposal taxes.

  • Inheriting

    Inheritance or estate tax, and succession rules.

  • Moving country

    How a change in tax residence affects the property.

  • Owning through an entity

    Company, trust or other structure implications.

The same property can trigger different tax questions at each stage.

Choose the right type of provider

Local tax specialist or cross-border private-client adviser?

  • Local or country specialist

    More relevant where the main issue is filing or tax compliance in one property jurisdiction. In this comparison: SpainFiscal and Estity, both for Spanish property.

  • Cross-border adviser

    More relevant where residence, estate planning, companies or several countries interact. In this comparison: Blevins Franks for its named European markets, and Equiom for private-client structuring.

For complex cases, both may be needed.

Common scenarios

Which property-tax situation is closest to yours?

Tools

Related tools

These tools compare a transfer cost or organise a move. They do not price a property or a mortgage.

Trying to budget tax on a property abroad?

Ask for the categories on this property — purchase, ownership, rent, sale and inheritance — before using anyone else’s percentage.

WiT Access provides general information and comparison resources. Property tax, purchase taxes, rental-income tax, capital gains, inheritance tax, reporting and tax-residency rules vary by jurisdiction and individual circumstances. Nothing on this page constitutes tax, legal, financial or investment advice.

WiT Access does not determine tax liabilities or whether a particular ownership structure is tax appropriate.

Cross-border property owners may need coordinated advice from qualified professionals in both the property jurisdiction and their country of residence.

WiT Access provides general information and comparison resources. Nothing on this page constitutes legal, tax, financial, mortgage, investment or property advice. Property rules, financing eligibility, taxes, fees and legal requirements vary by jurisdiction and individual circumstances.