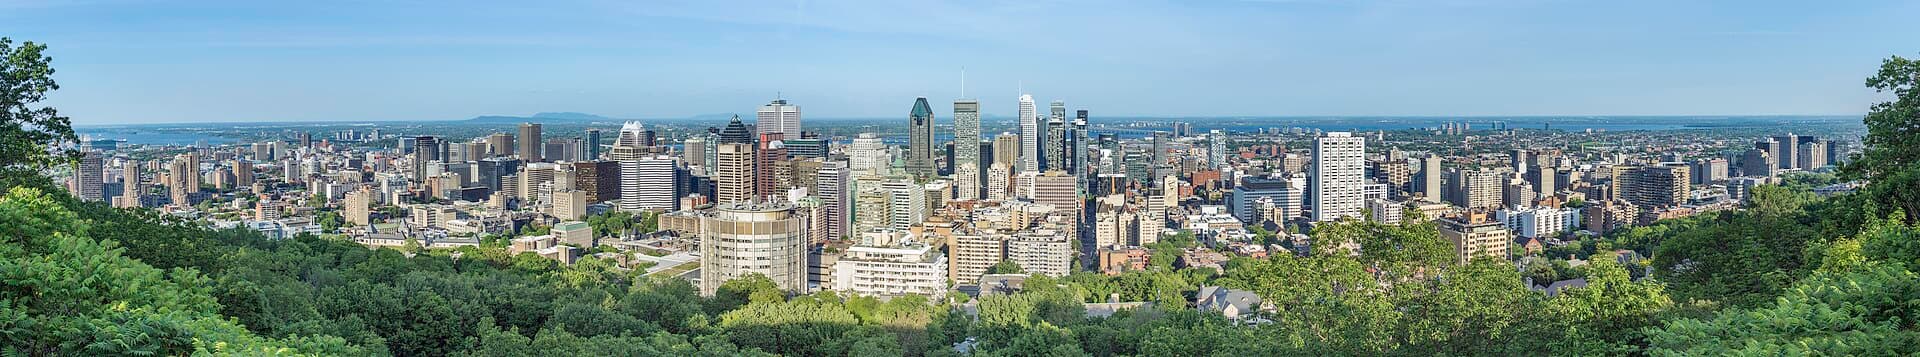
Destination
Moving to and managing money in Canada
Provincial differences, tax and banking for a move to Canada.
Canada combines federal immigration and tax rules with provinces that run healthcare, much of daily life, and their own income tax. Quebec is different again. A plan made for Toronto is not a plan for Vancouver or Montreal. This page stays general on purpose.
Residency
Permanent and temporary status are federal in structure, with provincial programmes that nominate people for some routes. The permit states whether you can work, and for whom.
Tax residence is its own test. You can be tax resident without being a permanent resident, and the year you arrive needs a careful day count.
Banking
Banks ask for identification and an address. New arrivals often open an account with the bank that will receive their pay. A social insurance number is part of ordinary setup once you are allowed to work.
Accounts you leave behind may need to be reported. Ask each provider whether a Canadian address is acceptable before you change it on the account.
Taxes
Federal tax and provincial tax both apply to residents, generally on worldwide income. The province of residence on 31 December often drives the provincial return. Moving between provinces in the year you arrive is worth flagging.
Registered accounts in Canada and investment accounts abroad do not travel cleanly. Do not move or close a portfolio without understanding the tax in both countries.
Property
Some provinces and cities have added taxes or restrictions aimed at foreign buyers. The rules are local and they change. Confirm the current rule for the city, not a headline from another year or another province.
A mortgage for a new arrival is a specialist conversation. Credit history from another country is not automatically accepted. Renting first is common.
Investments
Canadian registered plans have contribution and residency conditions. A pension or investment account from home may not accept new contributions once you leave, and withdrawals can be taxed in both places.
If you keep a broker abroad, ask whether they will still deal with you. Some will not, once you are resident in Canada.
Insurance
Public healthcare is run by the province. New residents often face a waiting period, and cover may not start the day you land. Bridge cover for that gap is worth buying before you fly.
Prescriptions, dental care and treatment outside your province are frequent gaps. Read them before you decline an employer plan.
Business
A Canadian employer, a foreign employer with you working from Canada, and a company you own are different for payroll, sales tax and your immigration conditions.
Province of operation matters for registration. So does whether you are allowed to work for yourself on the status you hold.
Moving money
Bringing savings to settle is normal. Banks and, sometimes, the tax return will ask for the source. Keep sale contracts and statements.
The Canadian dollar is the spending currency. Price conversions from sterling, euros or US dollars rather than converting everything on instinct at the airport.
Guides

Calculators and tools
Compare providers
WiT Access provides general information and comparison resources. Nothing on this website constitutes financial, tax, legal or investment advice. Always consider obtaining advice from an appropriately qualified professional.

Talk to someone about Canada
Tell us what you are considering. An enquiry is not a recommendation.